ESG reporting is the structured disclosure of an organization’s environmental, social, and governance performance through standardized metrics and narratives, typically published annually to demonstrate accountability to investors, regulators, and stakeholders. Companies measure and report data across carbon emissions, resource consumption, labor practices, diversity metrics, board composition, and ethical oversight, then package these findings into reports aligned with frameworks such as GRI, SASB, or TCFD.
The practice has shifted from voluntary corporate citizenship to a compliance imperative. Regulators in the European Union, United Kingdom, and California now mandate ESG disclosures for companies above certain size thresholds, and institutional investors increasingly make capital allocation decisions based on reported sustainability performance. If your organization operates facilities with significant energy consumption, manages wastewater systems, or sits within supply chains of covered entities, you likely face ESG reporting obligations whether through direct regulation or contractual pressure from clients and lenders.
Understanding who must report, which frameworks apply, and how to collect accurate baseline data separates organizations that treat ESG as a compliance burden from those that extract strategic value. A well-executed report identifies operational inefficiencies, quantifies emissions reduction opportunities, and positions your organization competitively for green financing. The process demands cross-functional coordination, from procurement teams tracking Scope 3 supplier emissions to HR departments compiling workforce diversity statistics, and facility managers monitoring energy and water use.
This guide walks you through the eligibility criteria that trigger reporting requirements, the step-by-step process to prepare compliant disclosures, your rights and obligations under current frameworks, and where to access expert support when navigating complex technical and regulatory requirements.
What ESG Reporting Is and Why Organizations Are Adopting It
ESG reporting is the systematic disclosure of non-financial performance data that measures how an organization manages environmental, social, and governance risks and opportunities. Unlike traditional financial reporting, ESG metrics capture the operational realities that shape long-term resilience: energy consumption and carbon emissions, water use and waste generation, workforce diversity and safety records, board composition and ethics policies. These disclosures translate abstract commitments into quantifiable data, kilowatt-hours saved, tons of CO2 avoided, hours of employee training delivered, percentage of independent directors, giving stakeholders a clear view of performance beyond the balance sheet.
The three pillars provide the framework. Environmental metrics track resource efficiency and ecological impact, from renewable energy procurement to wastewater treatment and landfill diversion rates. Social data covers labor practices, community investment, supply chain standards, and health and safety performance. Governance disclosures address executive compensation, board oversight, anti-corruption measures, and compliance systems. Together, they form a comprehensive picture of how an organization operates within its broader ecosystem.
Organizations are adopting ESG reporting for three converging reasons. First, regulatory mandates are expanding rapidly. The SEC’s climate disclosure rules require publicly traded companies to report material climate risks and emissions data. The EU Corporate Sustainability Reporting Directive applies to large companies and listed SMEs, standardizing requirements across member states. California’s climate laws mandate Scope 1, 2, and 3 emissions disclosure for companies doing business in the state. What began as voluntary practice for sustainability leaders is becoming a compliance baseline in 2026.
Second, investor and lender expectations have hardened. Institutional investors managing trillions in assets now integrate ESG data into due diligence, portfolio management, and proxy voting. Banks and insurers assess climate risk and energy sustainability performance when underwriting loans and policies. Companies without credible ESG disclosures face higher capital costs and limited access to sustainable finance products.
Third, ESG data strengthens internal risk management and strategic planning. Tracking energy use identifies efficiency opportunities and cost savings. Monitoring emissions exposes regulatory and transition risks tied to carbon pricing. Measuring workforce metrics reveals retention challenges and skills gaps. ESG reporting transforms business sustainability from aspiration to operational discipline, embedding accountability into decision-making and connecting today’s resource management to tomorrow’s competitive position.
Who Must Report: Eligibility Requirements and Thresholds
ESG reporting requirements in 2026 depend on jurisdiction, organization size, industry sector, and business relationships. Publicly traded companies face the most stringent mandates, but private firms, universities, hospitals, and government agencies increasingly encounter reporting obligations through regulation, supply chain demands, and stakeholder expectations.
In the United States, the SEC’s climate disclosure rules require public companies to report Scope 1 and Scope 2 greenhouse gas emissions, climate-related risks, and governance structures for climate oversight. Large accelerated filers, those with public float above $700 million, face the most comprehensive requirements, including assurance of climate data. Smaller reporting companies may qualify for scaled disclosure or extended compliance timelines, but the direction is clear: transparency on environmental performance is now mandatory for entities accessing U.S. capital markets.
The European Union’s Corporate Sustainability Reporting Directive (CSRD) casts a wider net. It applies to all EU-listed companies, large companies meeting two of three criteria, more than 250 employees, €40 million revenue, or €20 million in assets, and eventually extends to non-EU companies with substantial EU operations. Energy utilities, waste water treatment facilities, and environmental service providers operating in Europe must comply regardless of ownership structure. Reporting standards under CSRD demand detailed disclosures across all three ESG pillars, not just climate.
Industry-specific mandates add another layer. Energy sector companies, especially those involved in fossil fuel extraction or power generation, face scrutiny from the EPA and state environmental agencies. Waste water utilities often report environmental performance to regulatory bodies as part of operating permits. Environmental consultancies serving government contracts may encounter ESG disclosure requirements in procurement processes.
| Organization Type | Typical Threshold | Regulatory Driver | Voluntary Motivations |
|---|---|---|---|
| Public company | All sizes (scaled by filer status) | SEC climate rules, exchange listing standards | Investor relations, capital access |
| Large private firm | 250+ employees or €40M+ revenue (EU) | CSRD, supply chain laws | Customer requirements, pre-IPO readiness |
| SME / mid-market | Below regulatory thresholds | None (most jurisdictions) | Procurement eligibility, competitive differentiation |
| Energy / environmental sector | Varies by permit and jurisdiction | EPA, state agencies, EU Taxonomy | Stakeholder trust, operational benchmarking |
Organizations below mandatory thresholds often produce ESG reports to meet procurement requirements from larger clients, respond to investor due diligence questionnaires, or position themselves competitively in sustainability-conscious markets. Universities issuing green bonds, hospitals pursuing LEED certification, and government agencies implementing climate action plans voluntarily adopt ESG disclosure to demonstrate accountability and attract mission-aligned partners. The practical reality in 2026 is that even organizations without legal obligations find ESG reporting necessary to maintain business relationships and access funding.
How to Complete the ESG Reporting Process
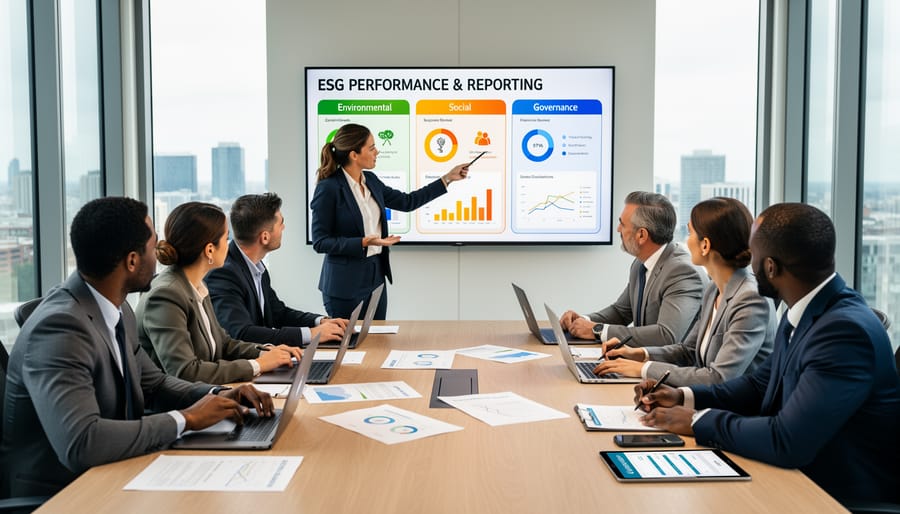
The ESG reporting process follows a structured cycle that organizations repeat annually or biannually, depending on stakeholder expectations and regulatory requirements. Start with a materiality assessment, the foundation of effective reporting. This involves identifying which environmental, social, and governance issues genuinely matter to your organization and stakeholders. Energy companies prioritize emissions and renewable energy integration, while hospitals focus on waste management and community health outcomes. Conduct stakeholder interviews with investors, customers, employees, and regulators to understand their information needs. Document the outcome: a materiality matrix that ranks issues by business impact and stakeholder concern.
Next, establish a cross-functional team to manage data collection. Assign clear ownership: facilities managers track energy consumption and water use, HR handles workforce diversity and safety metrics, finance oversees governance disclosures. Invest in an energy management system if you haven’t already, these platforms automate meter data collection and calculate Scope 1 and 2 emissions in real time. Set baseline metrics for your first reporting cycle. If historical data is incomplete, estimate using utility bills, operational records, and industry benchmarks. Record your methodology so future reports measure progress consistently.
Choose your reporting framework early. GRI suits organizations seeking comprehensive stakeholder communication. SASB appeals to investor-focused companies in specific industries like utilities or waste management. TCFD addresses climate-related financial risks. CDP serves organizations disclosing to customers and supply chain partners. Many entities use multiple frameworks to meet different audience needs. Align framework selection with your materiality assessment, if energy transition emerged as material, ensure your framework captures renewable energy procurement and customized green plans that reduce carbon intensity.
Integrate ESG data collection into existing compliance workflows. If you already track emissions for air permits or energy use for ISO 50001, repurpose that data for ESG reporting. This reduces burden and ensures consistency. Schedule quarterly data reviews to catch gaps before year-end reporting deadlines.
Draft your report using clear language and visual aids, charts showing emissions trends, tables comparing year-over-year energy savings, infographics illustrating workforce demographics. Be transparent about challenges and setbacks alongside achievements. Stakeholders value honesty over perfection.
Consider third-party assurance for credibility. External auditors verify data accuracy and reporting completeness, which strengthens investor confidence and satisfies regulatory requirements in some jurisdictions. Limited assurance (reviewing processes and sampling data) costs less than reasonable assurance (comprehensive verification) but still adds legitimacy.
Publish your report on your website and file it with relevant regulatory bodies. Communicate highlights through press releases, investor presentations, and stakeholder meetings. ESG reporting isn’t a one-time compliance exercise, it’s a continuous improvement cycle that reveals efficiency opportunities, informs capital allocation, and builds trust with the audiences that matter most to your organization’s long-term success.
Your Rights and Obligations as a Reporting Organization
Understanding your legal duties and protections under ESG reporting requirements helps you navigate disclosure obligations without jeopardizing competitive advantage or exposing your organization to unnecessary risk. The specifics vary by jurisdiction and company profile, but core principles apply across most frameworks.
Mandatory Disclosure Requirements
If your organization falls within regulatory scope, such as SEC climate disclosure rules or EU Corporate Sustainability Reporting Directive thresholds, you must disclose specified ESG metrics according to defined timelines. These typically include greenhouse gas emissions (Scope 1 and 2, with varying Scope 3 requirements), energy consumption data, governance structures, and material ESG risks. Energy-intensive sectors face additional scrutiny on carbon intensity and transition planning. Failure to report accurate, timely data can trigger regulatory enforcement actions, financial penalties, and mandatory corrective measures.
Protections for Sensitive Information
Most frameworks recognize that certain operational details, such as proprietary energy efficiency technologies, specific renewable energy procurement contracts, or facility-level consumption data, carry competitive sensitivity. You can typically aggregate data to protect trade secrets while still meeting disclosure thresholds. Framework guidance allows reasonable estimation methods when precise measurement is impractical or prohibitively expensive, provided you document your methodology and disclose limitations.
Consequences of Non-Compliance
Beyond regulatory fines, inaccurate or incomplete ESG reporting damages stakeholder trust. Investors may downgrade your sustainability ratings, procurement officers may disqualify bids, and employees increasingly evaluate employers on ESG performance. Material misstatements can trigger shareholder litigation and SEC enforcement in public markets. Reputational harm often exceeds direct penalties.
Your Rights During Implementation
Reporting organizations can phase implementation as frameworks evolve, starting with high-confidence data and expanding coverage over time. Safe harbor provisions in some jurisdictions protect forward-looking statements and good-faith estimates from liability, provided you clearly identify assumptions and uncertainties. You have the right to select frameworks aligned with your industry and stakeholder priorities, and to seek third-party assurance at a level appropriate to your resources and reporting maturity.
Selecting the Right ESG Framework for Your Industry
Choosing an ESG reporting framework isn’t a one-size-fits-all decision. Energy companies, waste water utilities, and environmental service providers face different stakeholder priorities, regulatory pressures, and disclosure expectations. The framework you select shapes what you measure, how you communicate performance, and which audiences you serve most effectively.
The Global Reporting Initiative (GRI) offers the most comprehensive approach, designed for multi-stakeholder transparency. It covers environmental, social, and governance topics in breadth and depth, making it ideal if your organization reports to customers, employees, communities, regulators, and investors simultaneously. Universities, hospitals, and government agencies often choose GRI because it addresses diverse accountability needs. For energy and environmental sectors, GRI provides detailed guidance on emissions, water use, waste management, and biodiversity impacts. The trade-off is resource intensity: GRI requires extensive data collection and cross-functional coordination.
The Sustainability Accounting Standards Board (SASB) takes an investor-first approach with industry-specific standards. SASB identifies financially material ESG issues for 77 industries, including Electric Utilities & Power Generators, Waste Management, and Water Utilities & Services. If your primary audience is investors or lenders, SASB delivers the metrics they care about most, carbon intensity, renewable energy mix, water stress exposure, regulatory compliance costs. SASB reports are leaner than GRI, focusing on what moves the needle financially. Many publicly traded energy companies use SASB to meet investor expectations efficiently.
The Task Force on Climate-related Financial Disclosures (TCFD) centers on climate risk and opportunity across four pillars: governance, strategy, risk management, and metrics. TCFD doesn’t prescribe specific metrics but requires organizations to disclose how climate change affects business resilience. Energy procurement strategies, physical risk to infrastructure (flooding, extreme heat), and transition risk from carbon regulation all fall under TCFD. Regulators increasingly mandate TCFD-aligned disclosure, making it essential for organizations with significant climate exposure.
The Carbon Disclosure Project (CDP) provides a questionnaire-based platform where companies disclose environmental data, climate change, water security, forests, to investors, customers, and cities. CDP scoring creates competitive benchmarking and supply chain pressure. Large energy users often request CDP scores from suppliers, making participation a procurement requirement. CDP aligns well with TCFD and complements other frameworks rather than replacing them.
Integrated reporting models, such as the International Integrated Reporting Framework, combine financial and ESG performance into a single narrative. These emerging approaches appeal to leadership teams seeking to demonstrate how sustainability drives enterprise value, but they require mature ESG data systems and board-level buy-in.
Your choice depends on three factors. First, audience: investors favor SASB and TCFD; regulators and communities expect GRI; customers increasingly demand CDP. Second, industry norms: check what peers report and what procurement partners require. Third, resource capacity: start with one framework that serves your most critical stakeholder group, then expand as systems mature. Many organizations phase in frameworks over two to three years, beginning with baseline measurement and materiality assessment before committing to comprehensive disclosure.
Where to Get Help: Resources, Tools, and Professional Support
Navigating ESG reporting becomes significantly easier when you know where to find reliable guidance and expert support. A range of official frameworks, government portals, and professional services exist to help organizations at every stage of the reporting journey.
Start with the framework providers themselves. The Global Reporting Initiative (GRI) maintains a comprehensive online standards database with sector-specific guidance for environmental and energy companies. The SASB Materiality Finder helps you identify which sustainability issues are financially material for your industry. The Task Force on Climate-related Financial Disclosures (TCFD) offers a Knowledge Hub with implementation resources, and CDP operates a disclosure platform where you can submit environmental data directly to investors and customers. Government agencies like the EPA provide sector-specific reporting protocols, while the SEC publishes guidance on climate disclosure requirements for public companies.
Essential resources for ESG reporting include:
- GRI Standards online database with sector-specific guidance
- SASB Materiality Finder for industry-relevant metrics
- TCFD Knowledge Hub for climate risk disclosure
- CDP disclosure platform for environmental data submission
- Industry association reporting guides for energy and waste water sectors
- ESG data management software for measurement and tracking
- Sustainability consultancies for strategy and implementation
- Third-party assurance firms for verification and credibility
Professional consultancies bring specialized expertise to complex reporting challenges. Firms like Sustainable Environment conduct materiality assessments tailored to your stakeholder priorities, design data collection systems that integrate with existing operations, and manage renewable energy procurement strategies that strengthen your environmental disclosures. Energy efficiency consultants can quantify savings from building retrofits and process improvements, providing credible data for Scope 1 and 2 emissions reporting.
For ongoing compliance and data quality, consider ESG management software platforms that centralize metrics, automate calculations, and generate reports aligned with multiple frameworks. When stakeholder scrutiny is high, third-party assurance providers verify your disclosures, adding credibility that investors and customers value.
How to Apply or Complete the Process
ESG reporting isn’t a single application you submit, it’s a recurring disclosure cycle you establish and repeat annually or as required by your stakeholders. Start by determining your reporting timeline. Most organizations align ESG reports with fiscal year-end, publishing within three to six months after closing their books. Mark these dates now and work backward to set internal milestones.
First, assemble your ESG working group. Pull representatives from finance, operations, HR, facilities management, and sustainability. Assign a project owner, typically a sustainability officer or CFO, who coordinates data requests and ensures deadlines are met.
Next, conduct your materiality assessment to identify which ESG topics matter most to your business and stakeholders. Energy consumption, greenhouse gas emissions, and Scope 3 emissions often rank high for energy and environmental firms.
Collect quantitative data from existing systems: utility bills, energy management platforms, HR records, procurement databases. Establish baseline metrics if this is your first cycle. Compile qualitative information about programs, policies, and governance structures.
Draft your report following your chosen framework’s structure. Have leadership review it for accuracy and strategic alignment. If pursuing third-party assurance, engage auditors early, verification takes four to eight weeks. Publish your report on your website, submit to disclosure platforms like CDP if required, and communicate key findings to investors and stakeholders.
Common ESG Reporting Questions Answered
Organizations new to ESG reporting often face similar questions about scope, timing, data quality, and compliance standards. Below are answers to the most common concerns from business leaders and sustainability officers navigating the reporting process in 2026.
How often must we report ESG data?
Most frameworks and regulations require annual reporting, typically aligned with your fiscal year. Some investors and CDP submissions request more frequent updates, quarterly or semi-annual, for material metrics like energy consumption and emissions.
What if we lack baseline data for prior years?
Start measuring now and establish your baseline with the current period. Frameworks permit phased implementation; disclose data gaps transparently and commit to expanding measurement over time.
Can we report estimated figures when exact data isn’t available?
Yes, reasonable estimation is acceptable if you document your methodology clearly. Use industry averages, engineering calculations, or proxy data, and note the estimation method in your report to maintain credibility.
When should we seek third-party assurance for our ESG report?
Pursue assurance when stakeholders demand verified data, common for public companies, regulated industries, and organizations seeking investor confidence. Limited assurance covers key metrics; reasonable assurance provides deeper validation similar to financial audits.
Scope 3 emissions, indirect emissions from your value chain, present the biggest challenge for most organizations. These include purchased goods, business travel, employee commuting, and product use. Start by focusing on the categories most material to your operations: for energy-intensive sectors, upstream fuel production and downstream distribution often dominate. You don’t need complete Scope 3 coverage immediately; frameworks allow phased disclosure as you build supplier engagement and data collection systems.
ESG reporting and carbon accounting overlap but serve different purposes. Carbon accounting quantifies greenhouse gas emissions across all three scopes, providing the environmental pillar data for ESG reports. ESG reporting encompasses this emissions data alongside social metrics (workforce diversity, safety records) and governance indicators (board independence, ethics policies). Think of carbon accounting as a specialized input feeding into the broader ESG narrative.
Renewable energy purchases affect your disclosures significantly. When you procure renewable energy certificates or enter power purchase agreements, you can claim market-based emissions reductions in Scope 2 reporting. Disclose both location-based emissions (grid average) and market-based emissions (reflecting your renewable procurement) to show the impact of your energy strategy. This dual reporting demonstrates your commitment to decarbonization while maintaining transparency about regional grid conditions.
ESG reporting in 2026 is more than a compliance checkbox. It’s a strategic tool that drives energy efficiency improvements, accelerates renewable energy adoption, and builds stakeholder confidence in your organization’s long-term resilience. Organizations that treat reporting as a disclosure exercise miss the opportunity to use ESG data for operational optimization, risk reduction, and market differentiation.
Start now, even if mandatory thresholds don’t yet apply to you. Conduct a materiality assessment to identify which environmental, social, and governance issues matter most to your stakeholders and operations. Establish baseline measurements for energy consumption, emissions, and key performance indicators. These early steps make future compliance seamless and reveal immediate opportunities for cost savings through efficiency gains.
You don’t have to navigate this alone. Proven frameworks like GRI, SASB, and TCFD provide clear roadmaps. Sustainability consultancies bring expertise in data collection, framework selection, and renewable energy procurement strategies that strengthen your disclosures. Organizations that engage early position themselves as sustainability leaders, attracting investors, customers, and partners who value transparency and forward-thinking environmental stewardship. The reporting journey starts with a single step, and the competitive advantage belongs to those who act first.